Friday, July 31, 2026

Dow Theory Update for July 31: Primary Bear Market in U.S. Bonds Reaffirmed on 7/29/2026


The bear market in bonds continues

General Remarks:

In this post, I thoroughly explained the rationale behind my use of two alternative definitions to appraise secondary reactions.

TLT is the iShares 20 plus Years Treasury Bond ETF. More about it here.

IEF is the iShares 7 to 10 Years Treasury Bond ETF. More about it here.

Thus, TLT tracks longer term US bonds, whereas IEF tracks middle term US bonds. A bull market in bonds entails lower interest rates. A bear market in bonds represents higher interest rates.

A) Market situation if one appraises secondary reactions not bound by the three weeks and 1/3 retracement dogma.

As I explained HERE, the primary trend was signaled as bearish on 5/19/2026. Following the 5/19/2026 bear market lows, a rally ensued, qualifying as a secondary (bullish) reaction against the primary bear market. The secondary reaction itself was signaled on 6/24/2026, and the volatility-adjusted bounce was completed on 6/29/2026, 27 trading days off the lows. Finally, a pullback on 7/13/2026 set up TLT and IEF for a potential primary bull market.

After the pullback, both ETFs headed lower over the following weeks. On 7/22/2026, IEF penetrated its 5/19/2026 primary bear market lows. On 7/29/2026, TLT broke down below its 5/19/2026 lows, providing confirmation. The Table below shows you the details:
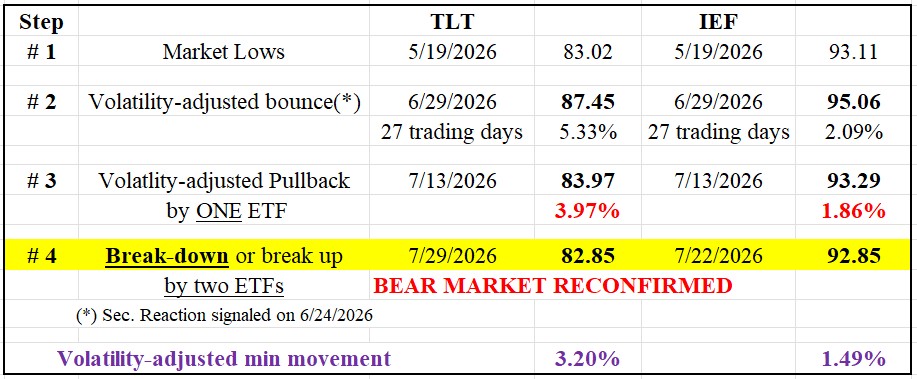
table TLT IEF

So, the implications of the newer lows are as follows:

1) The secondary reaction against the primary bear market has been terminated. Now the secondary trend is also bearish.

2) The setup for a potential primary bull market has been canceled.

3) The primary bear market signaled on 5/19/2026 has been reaffirmed.

The charts provide a visual representation of price action in the market over the past few months, spanning from the lows observed on 5/19/2026 to the present day. The blue rectangles will indicate the secondary (bullish) reaction against the primary bear market. The dark blue rectangles represent the pullback that set up both ETFs for a potential primary bull market. The red horizontal lines will highlight the primary bear market lows of 5/19/2026, which have recently been pierced.
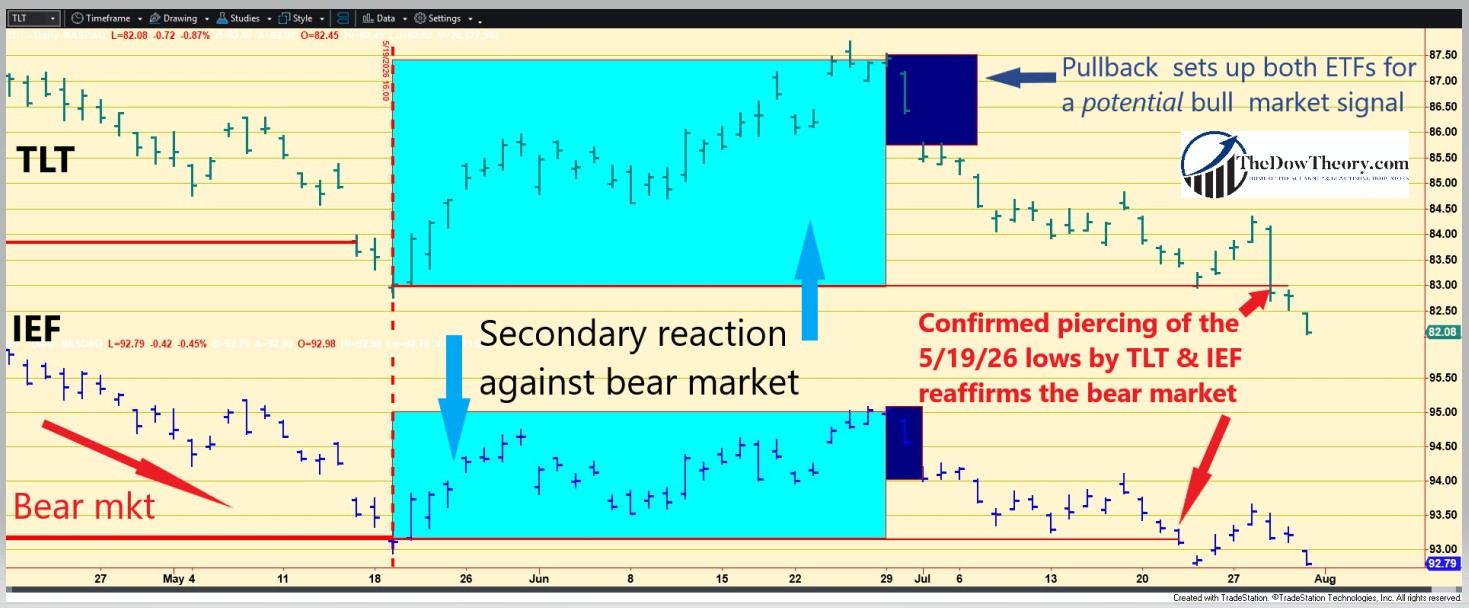
TLT IEF CHART EDITED

Therefore, it appears that the bond market continues to price in persistent inflationary pressure rather than the likelihood of an imminent recession. It is not necessarily a harbinger of a bear market in equities, but it may continue to limit their upside.

B) Market situation if one sticks to the traditional interpretation demanding more than three weeks and 1/3 confirmed retracement to declare a secondary reaction.

In this specific instance, the longer-term application of the Dow Theory aligns with the shorter-term rendering explained above. In other words, the price action and the Table shown above fully apply when we take the longer term view as well. Therefore, the primary trend shifted to bearish on 5/19/2026, and both the primary and secondary trends are bearish under this interpretation too.

Sincerely,

Manuel Blay

Editor of thedowtheory.com


Thursday, July 23, 2026

The Closest Thing to a Free Lunch in Investing


The Magic of Combining Strategies

One of the advantages of quantitative investing is that diversification can be engineered rather than left to chance.

I run several independent quant strategies. Within each one, I impose a strict rule: no single sector may account for more than 30% of the portfolio. That limit prevents any individual strategy from becoming overly concentrated. Still, a 30% allocation to one sector can be meaningful and a tad too high to my taste.

This is where the real magic begins.

Instead of relying on a single strategy, I combine four different strategies, each with its own stock-selection logic and sector profile, allocating 25% of the capital to each. The result is far more balanced than any of the individual strategies alone.

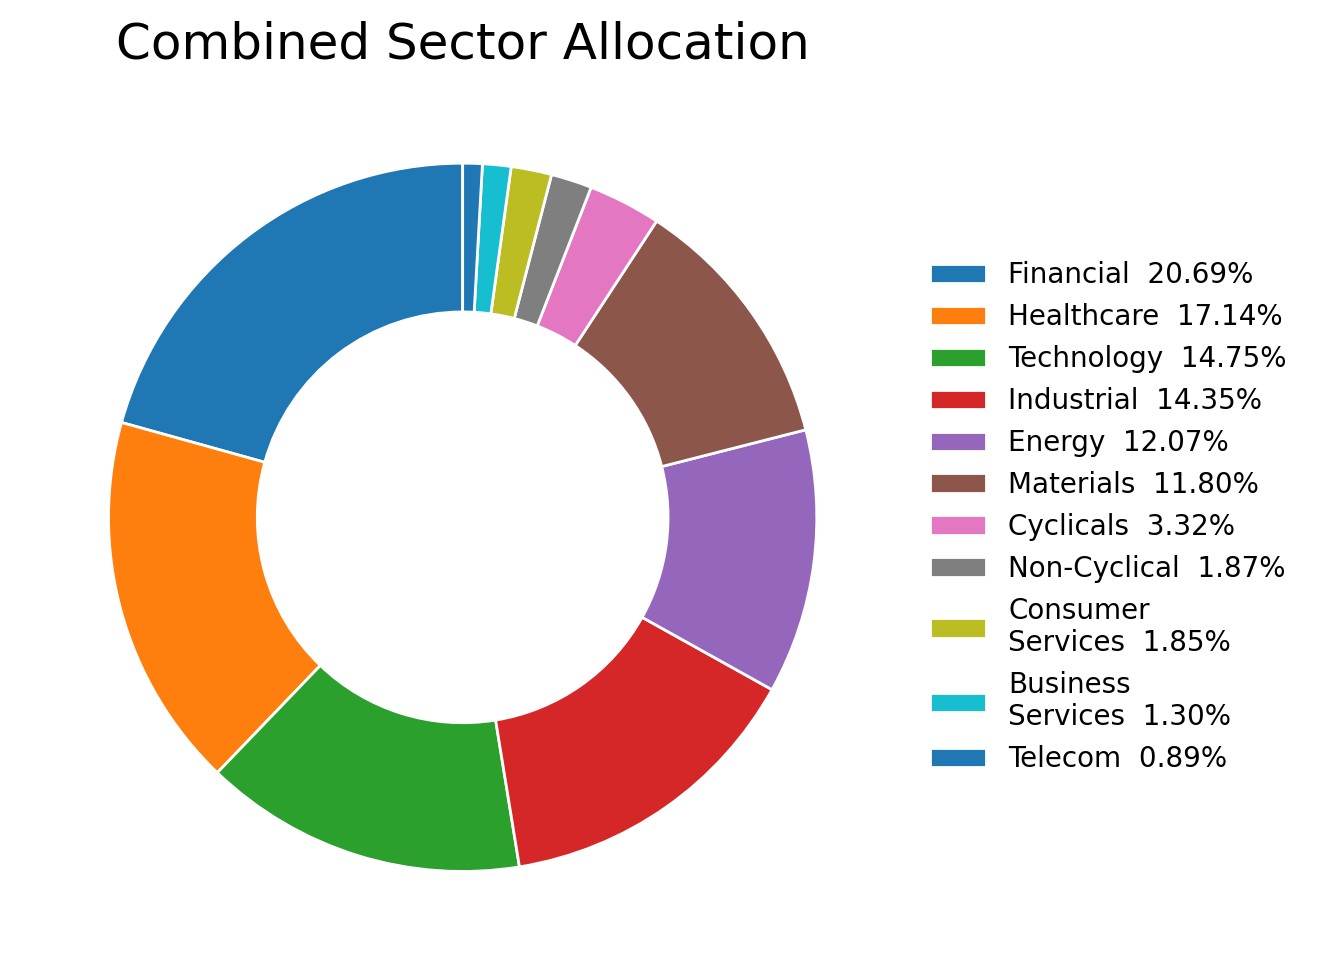
As the chart below illustrates, my current combined portfolio’s largest sector is Financials at just 20.69%, followed by Healthcare at 17.14%. No sector comes remotely close to the original 30% cap. The different strategies naturally offset one another, smoothing out sector concentrations without sacrificing their individual strengths.

408 Combined Sector Allocation

The same phenomenon extends beyond sectors. The combined portfolio also achieves a healthier mix of market capitalizations while preserving its intended exposure to the mid and small- cap universe.

This is one of the closest things to a free lunch in investing: by combining multiple robust strategies that behave differently, you reduce concentration risk and build a more diversified portfolio without diluting the edge of the underlying models.

And yes, you guessed it: by combining the four strategies, volatility is reduced, as are the spells of underperformance vs. the benchmark.

Furthermore, I was recently asked whether I planned to incorporate AI or quantum computing stocks into my portfolios. My answer was very simple: if they offer a high probability of outperforming over the next three months, my system will find them, and they will automatically appear on my buy list.

409 should i buy ai

That is one of the greatest advantages of a fully systematic, quantitative approach. I don’t have to spend my time trying to identify the next hidden gem or debating whether AI or quantum computing is the investment theme of the future. My job is simply to trust the process.

If AI or quantum stocks truly offer superior expected returns, my models will naturally allocate more capital to them within their respective sectors. If they don’t, they won’t make the cut. Rather than chasing narratives, I let my system do the work—and let the data make the decisions.

Sincerely,

Manuel Blay

Editor of thedowtheory.com
Wednesday, June 17, 2026

Some Lessons I Have Learned as a Quantitative Trader


Outperformance Comes in Bursts, Pain Comes in Stretches

What follows is based on my own experience as a quantitative trader. Other quants, using different models, different universes, or different constraints, may have reached different conclusions.

One of the first lessons I have learned is the importance of understanding the universe one is trading. I run one specific strategy focused on S&P 500 constituents, but most of my other strategies also include mid- and small-caps. I generally avoid microcaps because their low liquidity often makes backtests unrealistic and live trading difficult. It is very easy to produce extraordinary historical returns in illiquid stocks that cannot be replicated in the real world.

Even when I focus on relatively liquid small- and mid-caps with strong ranking profiles, the experience can be psychologically demanding. By ranking profile, I mean the relative attractiveness of a stock based on factors such as financial strength, business quality, growth, value, momentum, or a combination of several of these. In theory, a portfolio of highly ranked stocks should do well. In practice, the journey is rarely smooth.

What I have observed is that small and mid-caps often underperform the S&P 500 for extended periods. This can happen even when the strategy is fundamentally sound and has a strong long-term record. Over a two-year period, and often even over one year, my quantitative strategies have usually outperformed the S&P 500. But that outperformance does not usually come in a steady, comfortable way.

Instead, it often comes in bursts.

This is one of the most important lessons. A strategy may lag badly for months. You may see the S&P 500 rise 10% in five months while your own strategy is flat. That is not easy to endure. It feels as if something is wrong. It creates doubt. It tests your confidence in the model.

Then, suddenly, in a period of only six or eight weeks, the same strategy may gain 25% and leave the S&P 500 far behind. The brief burst of outperformance more than compensates for the long and frustrating period of underperformance.

This is why there is no free lunch. Quantitative strategies may deliver superior long-term results, but they demand psychological fortitude. It is not enough to have a good model. One must also have the temperament to stick with it when it is temporarily out of favor.

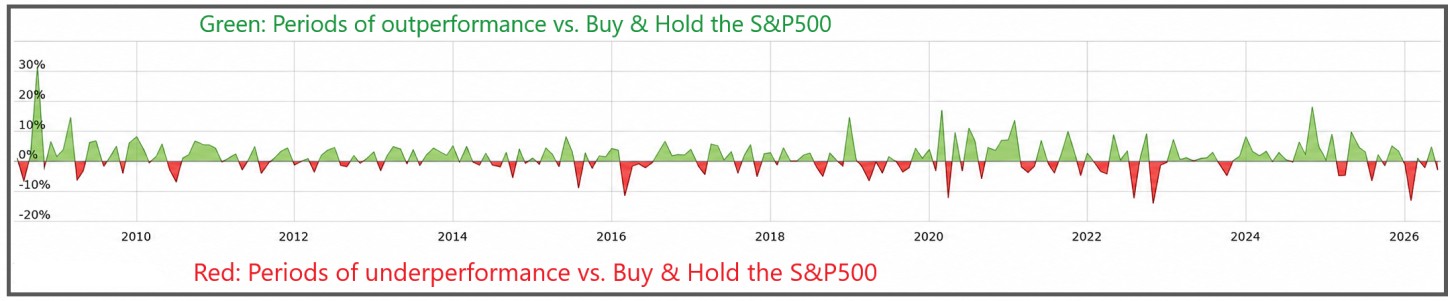
The screenshots below illustrate this point clearly. The first chart displays the periods of underperformance (in red) and outperformance (in green) of one of my quant-based trading strategies relative to a simple S&P 500 buy-and-hold approach.

405 periods of underperformance and outperformance vs buy and hold

What matters is not merely the final result. What matters is the path taken to get there. And the road may feel uncomfortable.

You can observe several spells of underperformance. In hindsight, they look tolerable. In real time, they are painful. They test your patience because you do not know whether the strategy is merely going through a normal bad stretch or whether something has genuinely stopped working.

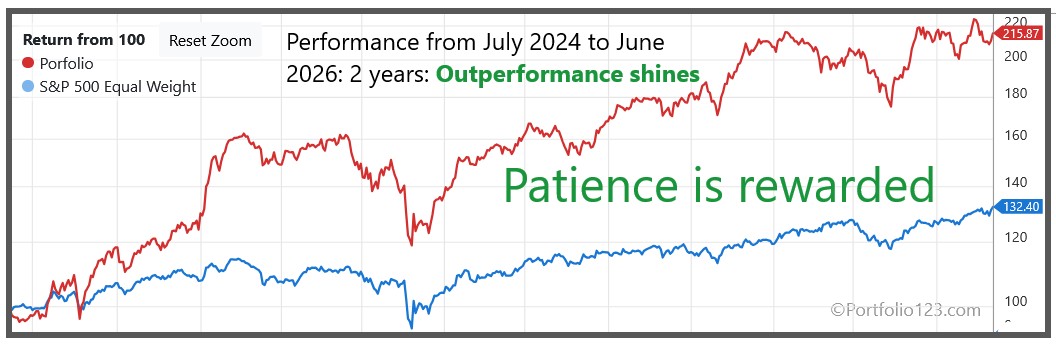
However, if we look back over two years, the picture changes completely, as shown in this chart:

406 periods of underperformance and outperformance vs buy and hold 2 years chart

The same strategy becomes a strong outperformer. And if we extend the view to almost 20 years, its long-term outperformance relative to the S&P 500 becomes even clearer.

Importantly, these results are not based on a frictionless theoretical exercise. A substantial slippage assumption of 0.25% per side of each trade has been included. That matters because, especially when trading smaller and mid-sized companies, ignoring slippage can make a strategy look much better on paper than it would have been in the real world.

The key takeaway is simple: patience is essential. The more your portfolio differs from the S&P 500, especially if it includes smaller companies, the more likely you are to underperform the index for extended periods. Your edge may not show up every month, or even every quarter. Often, it appears in short, powerful bursts that more than offset the painful spells of relative weakness.

That is the price of outperformance, and it is a price that can only be paid by those with the patience and psychological fortitude to stay the course when the going gets tough. In the end, that is often what separates the winners from the losers.

Sincerely,

Manuel Blay

Editor of thedowtheory.com
Wednesday, June 10, 2026

Gold and Silver miners ETFs Turn Bearish on 6/9/2026


Overview: In my June 1st Letter to subscribers, I noted that the two-year Treasury yield was breaking higher and that this would likely exert a negative influence on liquidity.

One of the main casualties appears to have been the gold and silver miners. On 6/9/26, a new bear market was signaled in both GDX and SIL. Gold and silver themselves have also been affected, as I discussed in this post.

Stocks, by contrast, have been affected only modestly so far. The decline has not even been enough to turn the secondary trend bearish. Therefore, both the primary and secondary trends for stocks remain bullish.

General Remarks:

In this post, I elaborate extensively on the rationale behind employing two alternative definitions to evaluate secondary reactions.

SIL refers to the Silver Miners ETF. More information about SIL can be found HERE.

GDX refers to the Gold Miners ETF. More information about GDX can be found HERE.

A) Market situation if one appraises secondary reactions not bound by the three weeks and 1/3 retracement dogma.  

As I explained in this post, the trend was signaled as bullish on 6/2/25.

Following a pullback (secondary reaction against the bullish trend), both GDX and SIL experienced a bounce, setting up both ETFs for a potential primary bear market signal. You can find detailed explanations and charts HERE.

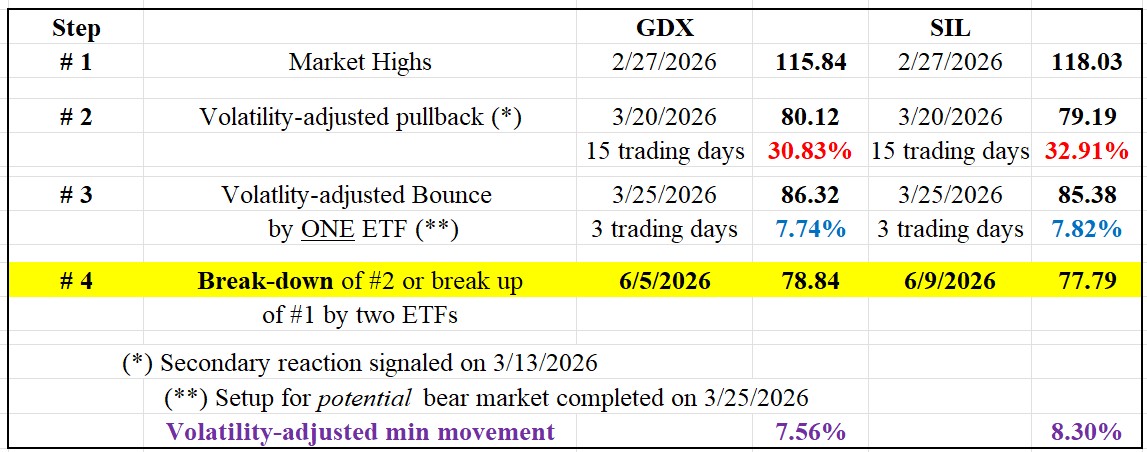
The table below gives you all the relevant information:

403 SIL GDX BEAR MKT JUNE 9 2026 TABLE

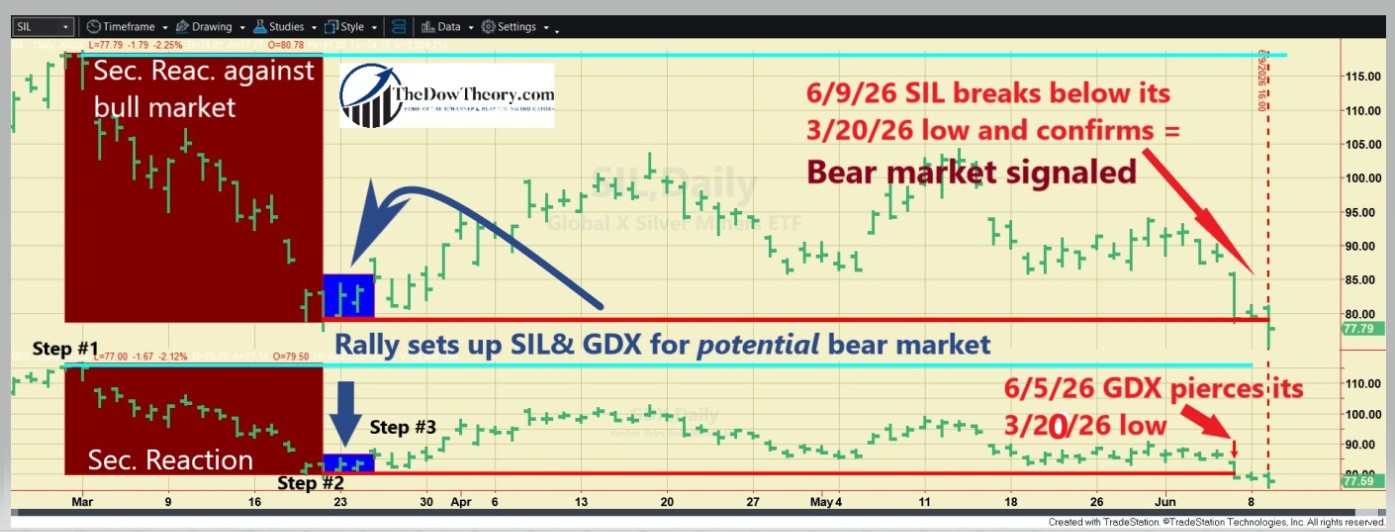
On 6/5/26, GDX broke down below its 3/20/26 pullback lows (Step #2). On 6/9/26, SIL confirmed by piercing its 3/20/26 closing lows. Since it was a confirmed violation, a primary bear market was signaled according to the Dow Theory.

Check out the chart below for a visual walkthrough of the recent price action. The brown rectangles highlight the secondary reaction (Step #2), the blue rectangles show the rally (Step #3) originating from the secondary reaction lows that set up both ETFs for a potential bear market signal, and the red horizontal lines pinpoint the pullback lows whose joint violation signaled the new bear market. The blue horizontal lines highlight the last recorded primary bull market highs (Step #1), whose upside breakout would signal a new primary bull market.

403 SIL GDX BEAR MKT JUNE 9 2026 edited 1


Thus, both the primary and secondary trends are currently bearish.

B) Market situation if one sticks to the traditional interpretation demanding more than three weeks and 1/3 confirmed retracement to declare a secondary reaction.

As I explained in this post, the trend was signaled as bullish on 6/2/25.

In this instance, the long-term application of the Dow Theory coincides with the shorter-term version, so there was a secondary reaction against the primary bull market, and the setup for a potential bear market signal has been completed. The confirmed violation of the 3/20/26 secondary reaction low triggered a bear market signal.

Thus, both the primary and secondary trends are currently bearish.

Sincerely,
Manuel Blay

Editor of thedowtheory.com
 

Tuesday, June 9, 2026

After a Long Ride, Gold and Silver Turn Bearish on 6/9/2026


Overview: In my June 1st Letter to subscribers, I noted that the two-year Treasury yield was breaking higher and that this would likely exert a negative influence on liquidity.

One of the main casualties appears to have been gold and silver. Today, 6/9/26, a new bear market was signaled in both metals. Gold and silver miners have also been hit, and I will address them in a separate post.

Stocks, by contrast, have been affected only modestly so far. The decline has not even been enough to turn the secondary trend bearish. Therefore, both the primary and secondary trends for stocks remain bullish.

General Remarks:

In this post, I extensively elaborate on the rationale behind employing two alternative definitions to evaluate secondary reactions.

GLD refers to the SPDR® Gold Shares (NYSEArca: GLD®). More information about GLD can be found HERE.

SLV refers to the iShares Silver Trust (NYSEArca: SLV®). More information about SLV can be found HERE.

A) Market situation if one appraises secondary reactions not bound by the three weeks and 1/3 retracement dogma.  

As I explained in this post, the primary trend was signaled as bullish on 4/2/24.

Following a pullback (secondary reaction against the bullish trend), both GLD and SLV experienced a bounce, setting up both ETFs for a potential primary bear market. You can find detailed explanations and charts HERE.

The table below gives you all the relevant information:

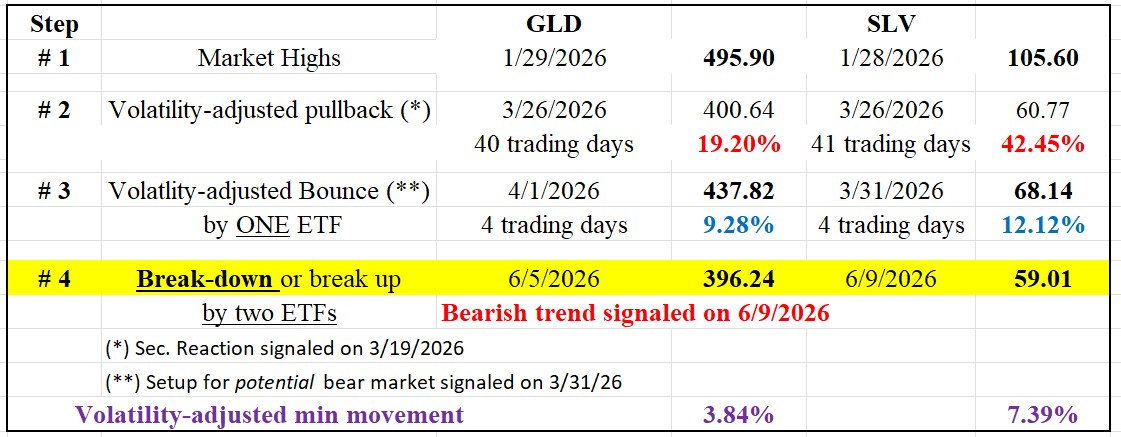
402 Table GLD SLV BEAR MARKET JUNE 9 2026

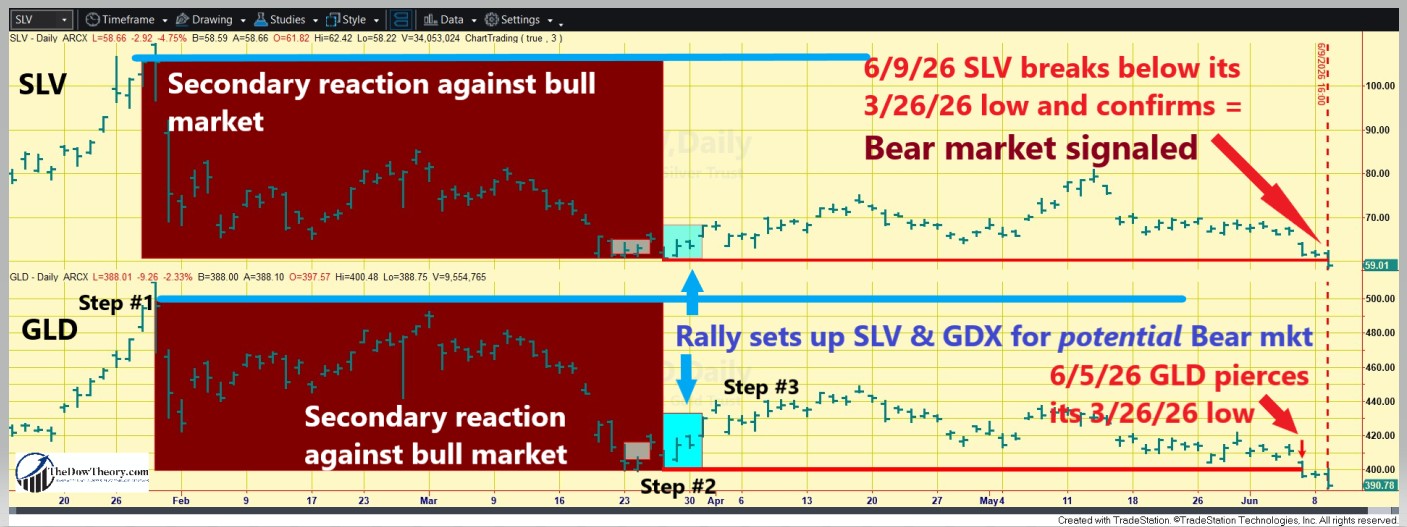
On 6/5/26, GLD broke down below its 3/26/26 pullback lows (Step #2). On 6/9/26, SLV confirmed by piercing its 3/26/26 closing lows. Since it was a confirmed violation, a primary bear market was signaled according to the Dow Theory.

Check out the chart below for a visual walkthrough of the recent price action. The brown rectangles highlight the secondary reaction (Step #2), the blue rectangles show the rally (Step #3) originating from the secondary reaction lows that set up both ETFs for a potential bear market signal, and the red horizontal lines pinpoint the pullback lows whose joint violation signaled the new “bear market.” The blue horizontal lines highlight the last recorded primary bull market highs (Step #1), whose upside breakout would signal a new primary bull market.

402 SLV GLD BEAR MARKET JUNE 9 2026 edited

Thus, both the primary and secondary trends are currently bearish.

B) Market situation if one sticks to the traditional interpretation demanding more than three weeks and 1/3 confirmed retracement to declare a secondary reaction.

As I explained in this post, the primary trend was signaled as bullish on 4/2/24.

In this instance, the long-term application of the Dow Theory coincides with the shorter-term version, so there was a secondary reaction against the primary bull market, and the setup for a potential bear market signal has been completed. The confirmed violation of the 3/26/26 secondary reaction low triggered a bear market signal.

Thus, both the primary and secondary trends are currently bearish.

Sincerely,
Manuel Blay

Editor of thedowtheory.com
Tuesday, June 2, 2026

Earnings Beat Valuations: Why the U.S. Still Leads


Do Not Underestimate America’s Earnings Machine

Do you remember when, just a few months ago, many experts insisted that U.S. stocks were too expensive, while Europe, and even China, offered the real value?

I never bought into that thesis.

At the time, I wrote several posts (here, here, here and here) warning that so-called “cheap” markets can easily become value traps. Low valuations alone are not enough. A market may look inexpensive for a reason, especially when earnings growth, innovation, capital allocation, and structural competitiveness are lacking.

That is why I was never persuaded by the simplistic argument that “Europe is cheap and the U.S. is expensive.” Cheapness is not a strategy. Earnings are.

Now Bloomberg (reproduced here without a paywall) seems to be reaching a similar conclusion. As Bloomberg reported:

I don’t think I remember a time that sell side consensus missed actual earnings number by so much,” said Charles Henry Monchau, chief investment officer at Banque Syz & Co SA. He began the year positioned for international markets to outperform, but the war and AI boom prompted him to tactically shift back toward US stocks, noting that regions such as China and Europe “might not be the winners of this war (emphasis supplied).”

The lesson is clear.

Do not blindly trust consensus. Do not blindly trust the experts. And above all, do not underestimate the United States.

In the end, earnings matter. And unless something changes drastically, the U.S. remains the undisputed leader in earnings generation. Energy independence, relentless innovation, a flexible labor market, relatively lower taxation and lighter regulation, and, whether some like it or not, unmatched military strength all reinforce America’s ability to create, scale, and protect profit generating businesses. Valuation arguments may sound persuasive in theory, but markets ultimately reward companies and economies that deliver profits, innovation, and growth.

The chart below shows the whole story:

Article content

Sincerely,

Manuel Blay

Editor of thedowtheory.com
Wednesday, May 20, 2026

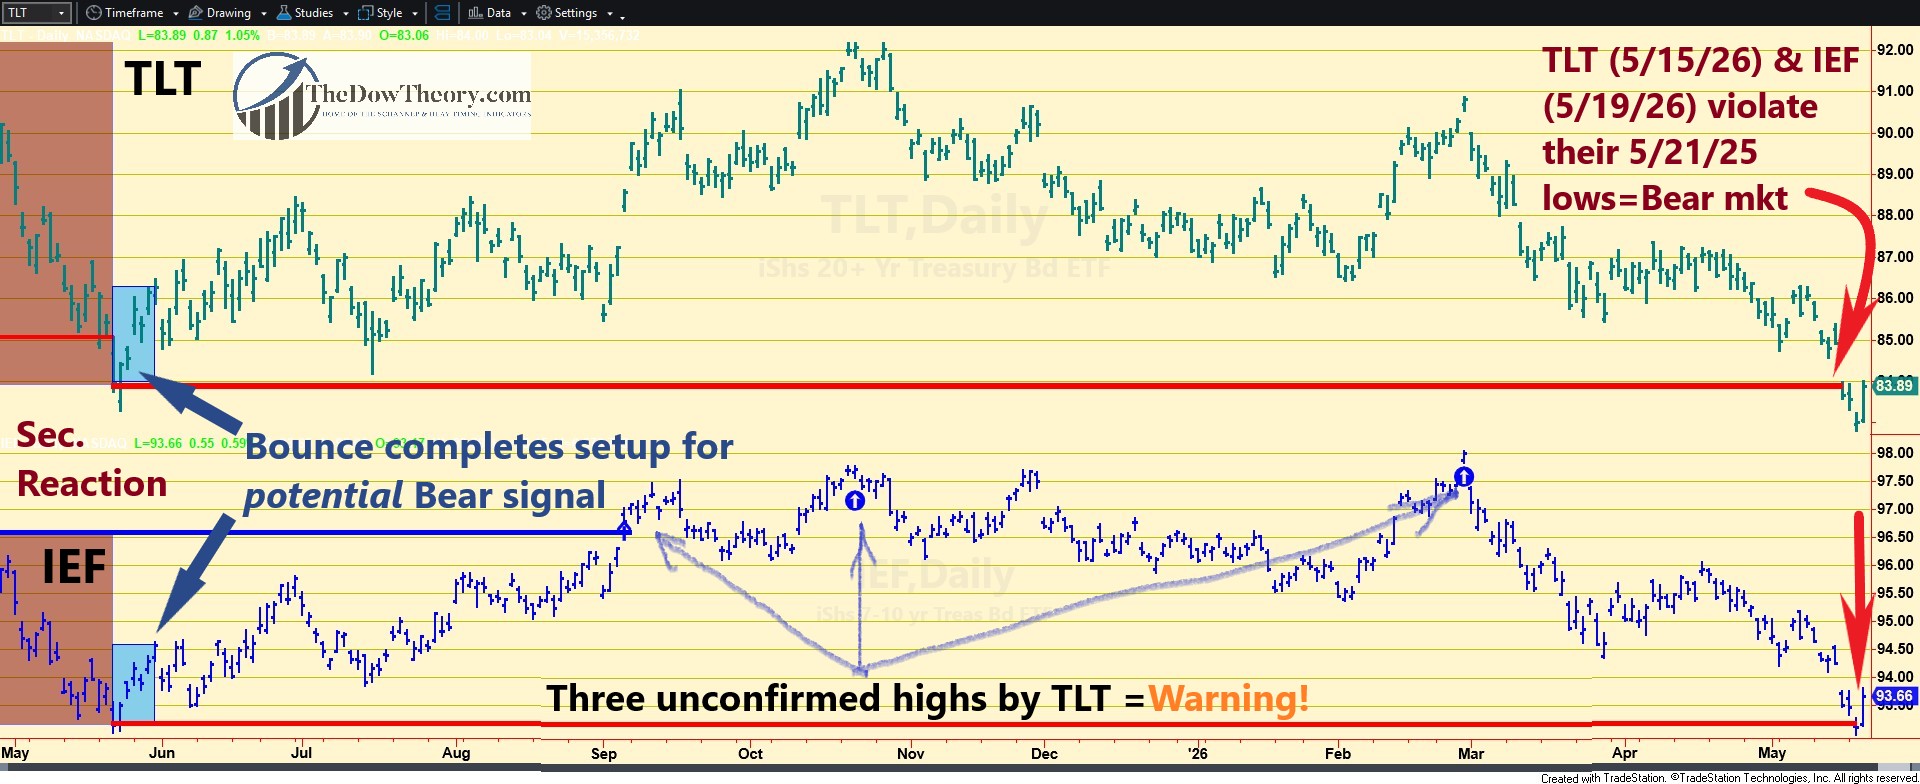
Dow Theory Signals Bear Market in Bonds on 5/19/2026

 Once again, the principle of confirmation gave a warning.


Overview: High crude oil prices are finally exerting inflationary pressure. With year-over-year CPI at 3.8%, bond yields have finally succumbed, and a new bear market in bonds, implying higher interest rates, was signaled on 5/19/26

As higher interest rates seem to be fueled by rising inflation rather than by higher real rates linked to stronger productivity, this creates another headwind for stocks. It is not necessarily a harbinger of a bear market, but it may limit their upside.

The principle of confirmation once again saved investors from adding to their position on three upside breakouts by IEF. In the three instances, TLT refused to confirm, making the breakouts suspect. More about how the principle of confirmation can save your skin in this post (and links therein)

General Remarks:

In this post, I extensively elaborate on the rationale behind employing two alternative definitions to evaluate secondary reactions.

TLT refers to the iShares 20+ Year Treasury Bond ETF. You can find more information about it here

IEF refers to the iShares 7-10 Year Treasury Bond ETF. You can find more information about it here.

TLT tracks longer-term US bonds, while IEF tracks intermediate-term US bonds. A bull market in bonds signifies lower interest rates, whereas a bear market in bonds indicates higher interest rates.

A) Market situation if one appraises secondary reactions not bound by the three weeks and 1/3 retracement dogma 

As I explained in this post, the trend was signaled as bullish on 4/4/25.

A rally ensued after the 5/21/25 lows (Step #3), which lasted for >=2 days with IEF exceeding its VAMM. Please remember that we don’t require confirmation for the final rally that completes a bear (or bull) signal setup. More information is in this post.

On 9/25/25, IEF surpassed its 4/4/25 bull market highs, unconfirmed by TLT. Again, on 10/22/25, IEF made an unconfirmed higher high.

Finally, on 2/27/26, IEF made an even higher high, while TLT failed even to exceed its previous local highs. A glaring non-confirmation.

Such a non-confirmation is not a bear market signal, but it was a yellow light: the IEF breakouts were suspect and therefore not enough to cancel the secondary (bearish) reaction.

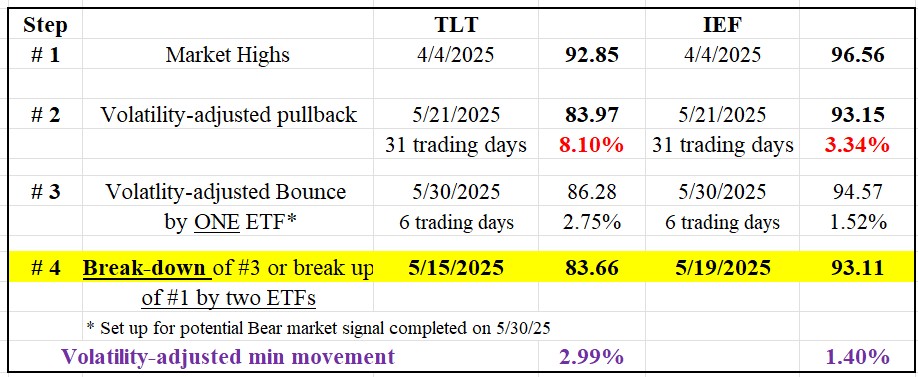
On 5/15/26, TLT violated its 5/21/25 secondary reaction lows. On 5/19/26, IEF confirmed by piercing its 5/21/25 secondary reaction lows. Confirmation means that a new primary bear market in bonds has been signaled.

The table below shows the price action that led to the primary bear market signal:

Table bond prices

So, the primary and secondary trends are bearish now.

The following charts depict the latest price movements. Brown rectangles indicate the secondary (bearish) reaction opposing the ongoing primary bull market. Blue rectangles highlight the rally that completed the setup for a potential primary bear market (Step #3). Red horizontal lines mark the secondary reaction lows (Step #2). The blue horizontal lines show the bounce highs (Step #3). A breach of these peaks would signal a new primary bull market, though this scenario appears unlikely in the near term.

TLT IEF POST edited

So, the situation is as follows: At the current juncture, a breakout on a closing basis by both TLT and IEF above their 4/4/25 closing highs (Step #1) would signal a new bull market. Until this breakout occurs, we consider bonds to be in a bear market.

B) Market situation if one sticks to the traditional interpretation requiring more than three weeks and 1/3 confirmed retracement to declare a secondary reaction.

As I explained in this post, the primary trend shifted to bullish on 4/4/25.

In this instance, the long-term application of the Dow Theory aligns with the shorter-term version, and hence the primary trend shifted to bearish on 5/19/26

Sincerely,

Manuel Blay

Editor of thedowtheory.com